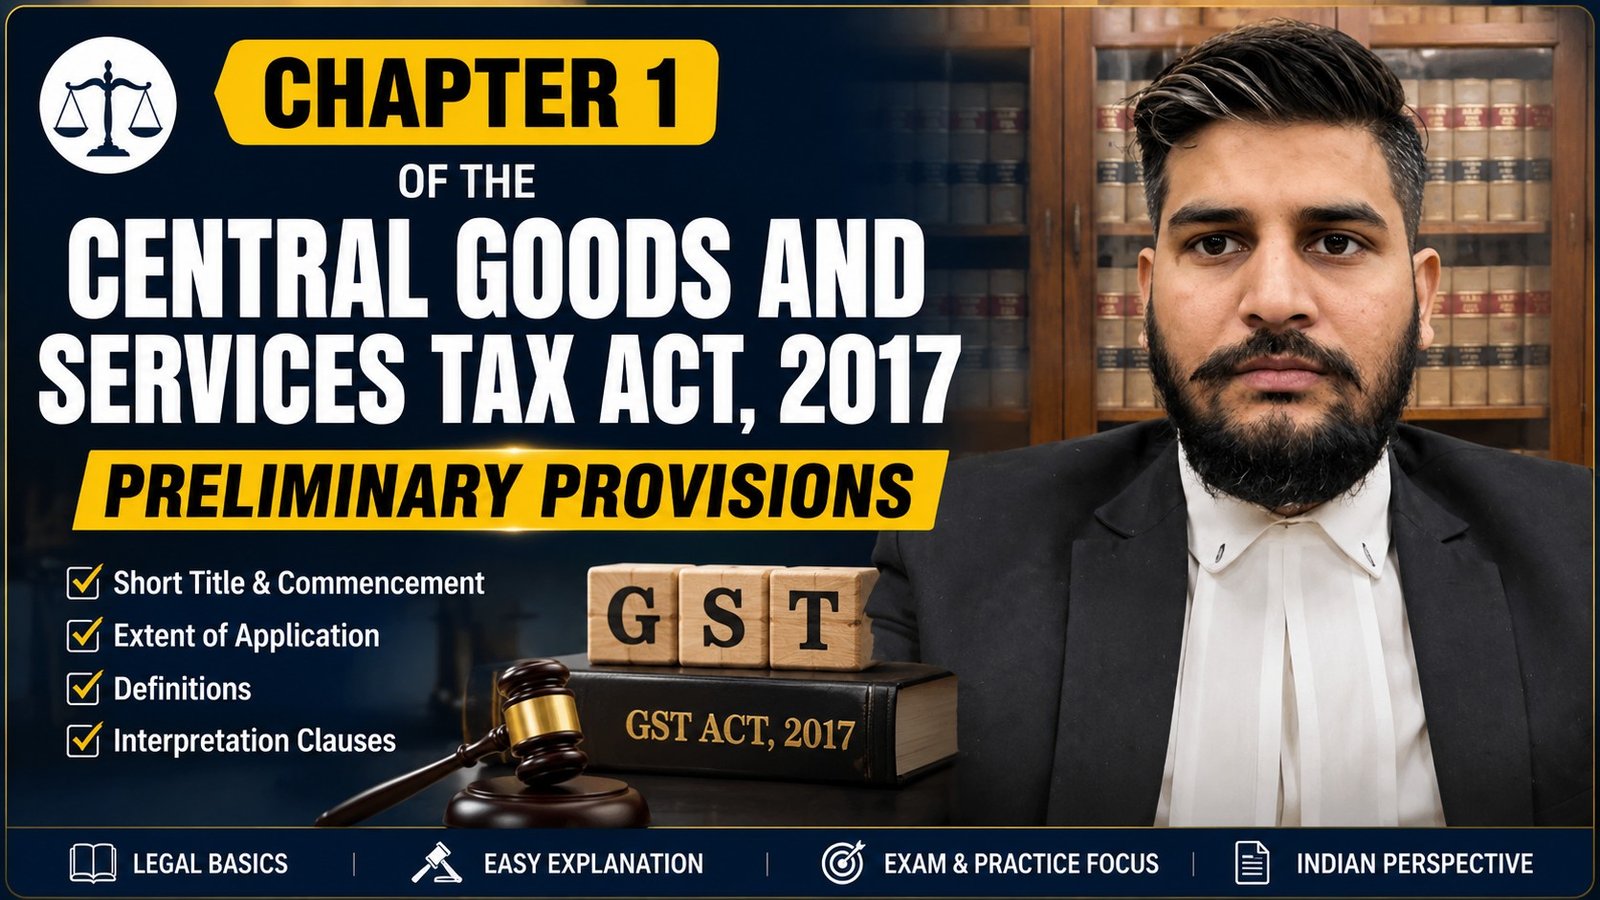
Chapter I of the Central Goods and Services Tax Act, 2017: Preliminary Provisions
Introduction
The Central Goods and Services Tax Act, 2017 (CGST Act) represents a landmark reform in India’s indirect taxation system. Enacted on April 12, 2017, this legislation operationalized the Goods and Services Tax (GST) regime, replacing the complex multi-layered tax structure that had prevailed for decades[1]. Chapter I of the CGST Act, titled “PRELIMINARY,” establishes the foundational framework of the legislation through two critical sections: Section 1 dealing with the short title, extent, and commencement, and Section 2 providing comprehensive definitions that govern the interpretation and application of the entire Act.
This article provides an exhaustive analysis of Chapter I, explaining its provisions, their legal significance, and practical implications for businesses, tax professionals, and legal practitioners operating under the GST regime.