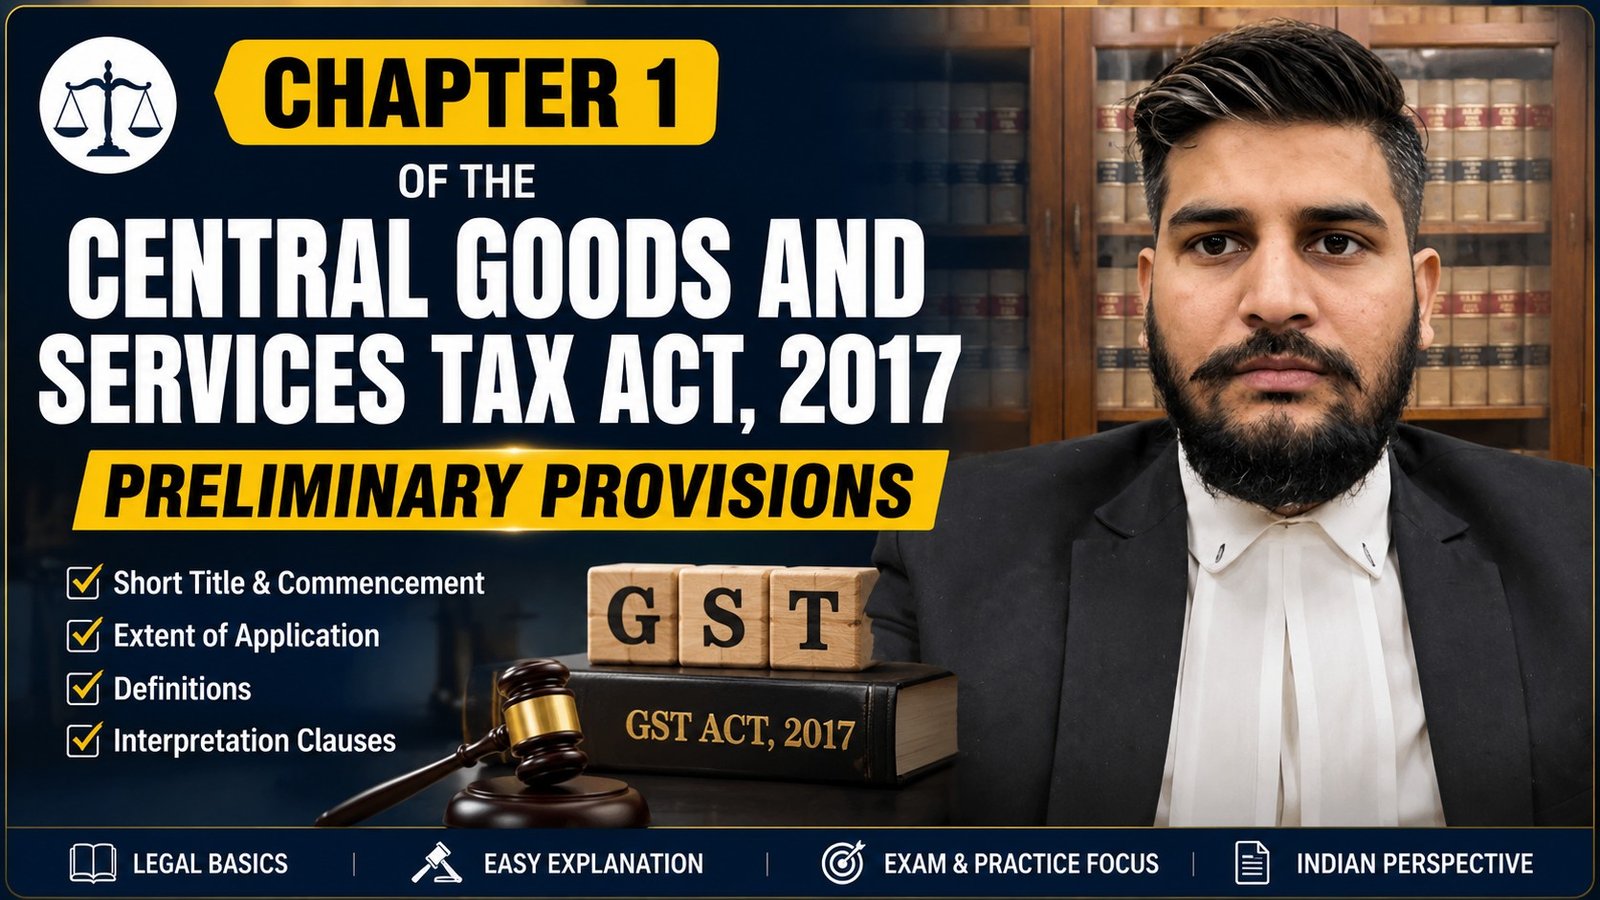
Chapter I of the Central Goods and Services Tax Act, 2017: Preliminary Provisions
Conclusion
Chapter I of the Central Goods and Services Tax Act, 2017, though comprising only two sections, establishes the essential foundation for the entire GST framework. Section 1 defines the law’s identity, jurisdiction, and implementation timeline, while Section 2 provides the comprehensive definitional architecture that governs interpretation of all subsequent provisions.
The phased implementation approach demonstrated the government’s commitment to ensuring smooth transition to the GST regime. The extension to Jammu and Kashmir fulfilled the vision of truly unified national taxation[1][4].
The extensive definitions in Section 2 reflect the complexity of modern commerce and the need for precision in tax legislation. These definitions eliminate ambiguity, reduce litigation, and facilitate uniform tax administration across India. They form the interpretative lens through which all GST provisions must be understood[2][5].
For businesses, understanding these preliminary provisions is not merely an academic exercise but a practical necessity for compliance, planning, and risk management. For tax professionals and legal practitioners, mastery of these definitions is indispensable for effective advisory and representation. For tax administrators, these provisions provide the tools for consistent and fair tax administration.
As the GST regime continues to evolve through amendments, notifications, and judicial interpretation, the foundational provisions of Chapter I remain the stable cornerstone upon which the entire edifice of India’s indirect taxation system rests. The success of GST as a transformative tax reform depends significantly on proper understanding and application of these preliminary provisions.